
15 Powerful Personal Finance Rules That Work
Confused about saving, spending and investing every month? These personal finance rules simplify money decisions so you save more and stress less.
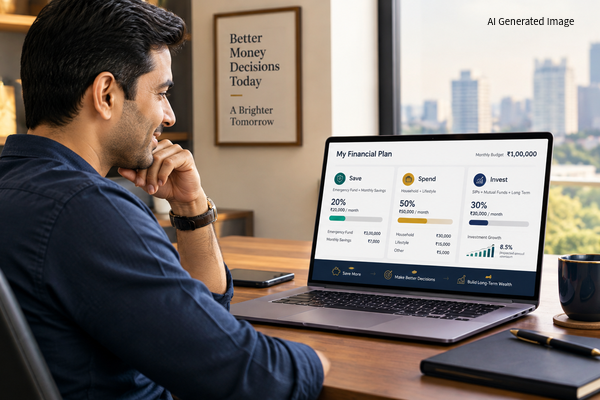
Most people don’t actually have a money problem. They have a money decision problem.
Salary hits the account, and the questions start immediately. How much should I save? Can I afford this? Should I take that loan? Every month, you’re back to square one, making the same calls on pure willpower, and willpower runs out faster than your bank balance does.
The fix isn’t another budgeting app. It’s a set of personal finance rules you decide once, when you’re calm, so your money moves on autopilot even when life gets noisy. Here’s how to build a system that fits your income and your real life, not someone else’s spreadsheet.
What Are Personal Finance Rules, Really?
Think of personal finance rules as your own money constitution, decisions you make in advance about how you’ll earn, spend, save, invest, borrow and protect your money, so you’re not renegotiating with yourself every time.
Instead of asking “should I invest this month,” your rule already says “I invest first, then I spend what’s left.” That one shift changes how money behaves in your life.
Why You Need a System, Not Just Motivation
Money decisions are emotional. You spend more when happy, shop when stressed, and get bold with investments right when the market is peaking. Without clear personal finance rules, your financial behaviour swings with your mood, not your goals.
A solid set of rules helps you control impulse spending, build an emergency fund, invest consistently and protect your family, without needing extra motivation on a random Tuesday.
Rule 1: Pay Yourself First
Flip the usual order. Instead of income minus expenses minus whatever’s left for savings, make it income minus savings minus expenses.
Say you earn ₹80,000 a month. Decide that ₹20,000 goes straight into savings and investments the moment your salary lands, leaving ₹60,000 for actual living. There’s rarely anything left at month end to save “later,” so save first.
Rule 2: Put a Ceiling on Lifestyle Inflation
A salary hike feels great until your lifestyle grows at the exact same pace. New phone, extra dinners out, one more subscription, and six months later the raise has vanished without a trace.
A simple rule fixes this. Whenever income rises, send at least half the increase straight to investments. A ₹15,000 hike becomes ₹7,500 for your future and ₹7,500 for enjoying today. You still get to celebrate the raise, but your future gets one too.
Rule 3: Separate Wants From Needs
Rule 4: Use a Waiting Period for Impulse Buys
Online shopping makes spending dangerously easy. One rule solves most of it: wait before you buy. Under ₹2,000, wait 24 hours. Between ₹2,000 and ₹10,000, wait three days. Above ₹10,000, wait a full week
The exact numbers matter less than the pause itself. Purchases that feel urgent at 11 pm often look completely unnecessary by morning.
Rule 5: Build Your Emergency Fund First
Your investments can be doing wonderfully and then the car breaks down, or income takes a temporary hit. Without a cushion, you’re forced to sell investments at the wrong time or reach for a credit card.
Keep roughly three to six months of essential expenses somewhere easily accessible, leaning toward the higher end if your income is irregular. This fund isn’t an investment strategy. Its only job is liquidity when life doesn’t stick to the plan.
Rule 6: Match Investments to Your Timeline
Rule 7: Set a Personal Debt Rule
Debt itself isn’t the villain. A home loan or education loan can be genuinely useful. What quietly damages your finances is expensive consumer debt for things that lose value fast.
A good rule sounds like this: don’t take a loan for something you can’t comfortably afford without it. Before signing up for any EMI, check the total cost, meaning principal plus interest plus fees, not just the monthly number.
Rule 8: Increase Your SIP as Income Grows
Rule 9: Don't React to Market Headlines
Rule 10: Protect Your Income Before Chasing Returns
Rule 11: Don't Confuse Insurance With Investment
Rule 12: Track Your Net Worth, Not Just Your Income
Rule 13: Give Every Goal a Number and a Deadline
Rule 14: Build a Financial Freedom Rule
Rule 15: Give Yourself Permission to Spend
Building Your Own Financial Rulebook
Start small. Write down your income, expenses, loans and goals, then notice where your money actually disappears, whether it’s food delivery, impulse EMIs or unplanned shopping. Pick seven to ten non-negotiables and automate as many as possible.
Your rules should evolve too. What works at 25 won’t necessarily work at 40, especially after marriage, kids or a career change, so revisit your rulebook once a year or whenever life shifts.
The Golden Rule
Decide your money moves when you’re calm, not when the market is crashing or a flash sale notification pops up. You can’t remove emotion from money entirely, but you can build a system that stops emotion from making every decision for you.
You don’t need fifty rules or a finance degree. You need a handful of personal finance rules you’ll actually follow, even on days when motivation is nowhere to be found. Start with a few today, stick with them for a year, and look back. The improvement rarely comes from finding the perfect investment. It comes from making the same smart decision, again and again.