
Ultimate Personal Finance Dashboard Guide for 2026
Learn how to create personal finance dashboard in India that tracks income, expenses, savings investments, debt, insurance and financial goals in one place.
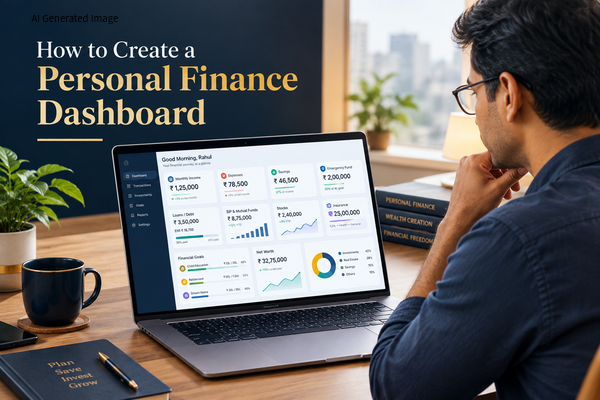
Ask yourself something honestly.
How much did you spend last month?
Not a guess. The actual number.
If you paused for more than five seconds, you are not alone. Most people are not bad with money because they earn too little or spend too much. They are bad with money because they cannot see it clearly. Your salary lands in one account, your SIPs sit in five different mutual funds, your credit card bill hides in an app you rarely open, and your insurance policy is buried somewhere in your email.
That scattered picture is exactly why a personal finance dashboard has become one of the most useful habits you can build in 2026. It is not a fancy tool. It is not a subscription you need to buy. It is simply one place where every rupee you earn, spend, save, owe and invest comes together so you can finally answer the question “where does my money actually go?”
What Exactly Is a Personal Finance Dashboard?
A personal finance dashboard is a single sheet, app or page that shows the complete picture of your money in one glance. Think of your car’s instrument panel. It does not show you every nut and bolt under the hood. It shows you speed, fuel and warning lights, the handful of numbers that actually matter while you are driving.
Your financial dashboard should do the same job for your money. Instead of jumping between five banking apps and a mental calculator, you look at one page and instantly know your income, expenses, savings, investments, debt, insurance cover and progress toward your goals.
Why a Dashboard Actually Changes How You Handle Money
Most Indian households do not lack financial products. They have a salary account, two or three SIPs, a credit card, maybe a home loan and a term plan. What they lack is a way to see all of it together.
Once you build a dashboard, three things happen almost immediately.
First, your real spending shows up. People often believe they spend around forty thousand rupees a month, only to discover the real figure is closer to fifty two thousand once food delivery, subscriptions and weekend spending are added up honestly.
Second, saving stops being a vague intention and becomes a measurable habit. “I should save more” turns into “my savings rate is 22 percent and I want to push it to 28 percent this year.”
Third, you start tracking net worth instead of just your salary slip. Net worth is calculated as total assets minus total liabilities, and watching this number grow over the years tells you far more about your financial health than a salary hike ever will.
The Building Blocks Every Personal Finance Dashboard Should Have
You do not need fifty categories to build a useful personal finance dashboard. You need seven honest sections.
Income tracker. List salary, freelance income, rental income, interest and dividends. If money entered your account as a loan or as a transfer from your own savings account, it is not income, so leave it out.
Expense tracker. Split spending into essentials such as rent, groceries and school fees, lifestyle spending such as dining out and shopping, and financial commitments such as EMIs and SIPs.
Savings rate. This one formula does most of the heavy lifting.
Savings Rate = Monthly Savings divided by Monthly Income, multiplied by 100
A person earning one lakh rupees who saves twenty five thousand every month is running a savings rate of 25 percent, which is a genuinely healthy number by most financial planning standards.
Emergency fund tracker. Multiply your essential monthly expenses by the number of months you want covered, usually six for salaried employees and closer to nine or twelve for freelancers and business owners whose income is less predictable.
Investment tracker. Record not just the amount in each mutual fund, stock or EPF account, but also its purpose. Money without a goal attached to it is far more likely to get redeemed the moment markets turn volatile.
Debt and EMI tracker. List every loan along with its outstanding balance, interest rate and EMI, then calculate your EMI to income ratio using this formula.
EMI to Income Ratio = Total EMIs divided by Monthly Income, multiplied by 100
Most financial planners consider anything above 40 percent a signal worth examining closely, though it is not an automatic red flag on its own.
Insurance and goals tracker. Note your term insurance sum assured, health cover for every family member and the target amount, current amount and deadline for each major goal such as a home down payment, your child’s education or retirement.
How to Actually Build a Personal Finance Dashboard in Excel or Google Sheets
You genuinely do not need expensive software to set up a personal finance dashboard.
Open Google Sheets and create separate tabs for Dashboard, Income, Expenses, Investments, Loans, Insurance and Goals. Feed your monthly numbers into each tab, then pull the key totals into the main Dashboard tab using simple SUM and formula links. Within an hour, you will have a working system that took most people years to build in their heads, imperfectly.
Add a splash of colour if it helps. A simple green, yellow and red flag system next to each goal (green for on track, yellow for needs attention, red for falling behind) makes the dashboard something you actually want to open every month instead of dreading it.
Ratios Worth Watching Every Month
Beyond savings rate and EMI to income ratio, a few more numbers are worth tracking.
Expense ratio tells you what percentage of income disappears into monthly spending. Investment rate shows how much of your income is actually being directed toward wealth building rather than just sitting idle. Debt to asset ratio, calculated as total debt divided by total assets, gives you a quick read on how leveraged your finances really are.
None of these numbers need to be perfect. They just need to be tracked consistently enough that you notice the direction they are heading.
Mistakes That Quietly Ruin a Good Dashboard
The most common mistake is trying to track everything, right down to the eighty rupees spent on chai. That level of detail burns you out within a month.
Another common trap is checking investment values every single day. Long term investments are meant to be reviewed quarterly, not obsessed over during every market dip.
People also tend to ignore insurance while building an impressive looking investment portfolio, which is a bit like building a beautiful house with no roof. And plenty of people count the home they live in as part of their retirement corpus, forgetting that you cannot spend a house you are still living inside.
Make Reviewing Your Dashboard a Habit, Not a Chore
You do not need to open your dashboard every day. A practical rhythm looks like this. Do a quick expense check weekly, update income, expenses, investments and loans monthly, review your asset allocation and insurance cover quarterly, and run a full financial health check once a year.
At the end of every month, spend twenty minutes asking simple questions. Did my expenses stay within plan? How much did I actually save and invest? Is my emergency fund still adequate? Am I moving closer to my goals or further away from them?
The Real Point of a Personal Finance Dashboard
A personal finance dashboard is not the destination. It is a decision making tool.
If your numbers show a low savings rate, a thin emergency fund and a heavy EMI burden, the fix is never a prettier spreadsheet. The fix is cutting a few lifestyle expenses, building your emergency fund faster or reviewing that debt before it grows further.
Start simple. Build one sheet. Track the handful of numbers that genuinely matter to your life. Review it once a month, and let it nudge you toward one better financial decision at a time. That single habit, more than any app or investment tip, is often what quietly separates people who feel in control of their money from people who are still guessing.